Russian coal exports to South Korea continued to grow in January-September 2026 as rising electricity demand and energy supply risks supported stronger coal imports.
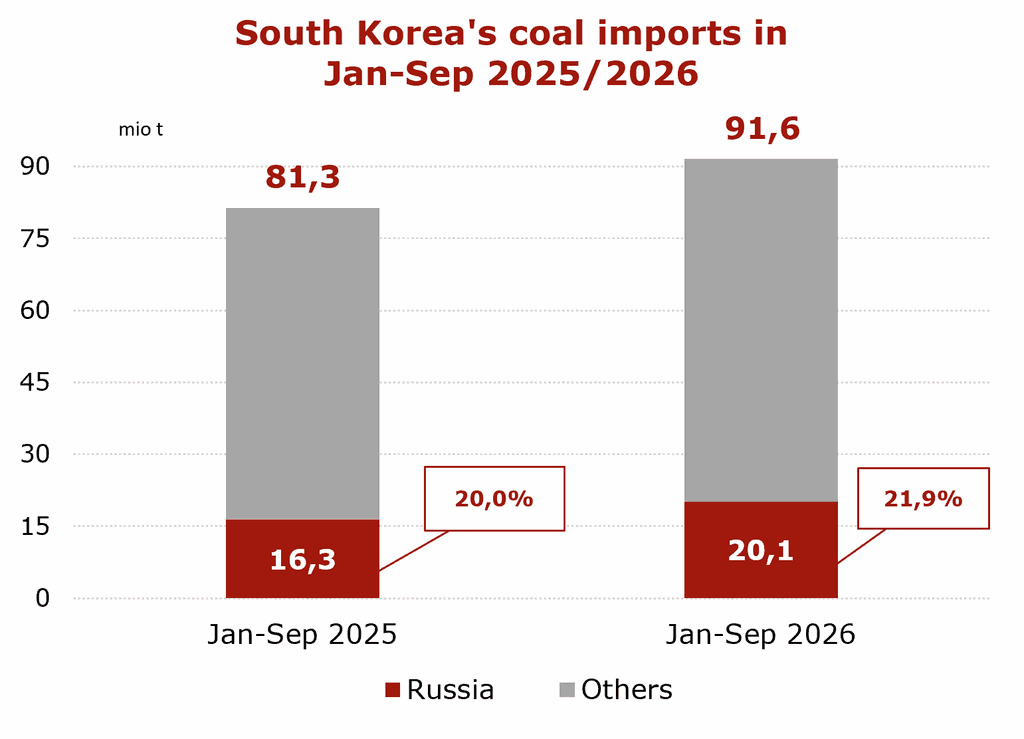
In January-September 2026, Russia increased its coal exports to South Korea to 20.1 mio t (+3.8 mio t or +23.3% vs. Jan-Sep 2025).
South Korea’s total coal imports in January-September 2026 surged to 91.6 mio t (+10.3 mio t or +12.7% vs. Jan-Sep 2025).
Because of the energy crisis in the Middle East, South Korea is lifting the 80% cap on coal-fired power plant capacity utilization and increasing nuclear power plant capacity utilization from the current 65–70% to 80%. With rising prices and supply risks for imported LNG and oil, coal and nuclear power generation are strengthening their positions in the country’s energy mix.
Furthermore, record-breaking demand for electricity, combined with the need to replenish reserves ahead of winter, as well as ongoing disruptions in global LNG supplies, may drive South Korea to sharply ramp up its thermal coal imports.
South Korean coal imports (January-September 2026):
Given the crisis in the Russian coal industry, South Korea remains strategically important due to comparatively higher prices than other key markets like China and India.
The unprofitability of Russian coal exports keeps growing because of expensive logistics and a strong ruble. Still, producers are trying to maintain their market share, owing to the quality of their material and expectations of better conditions in the medium term, including stabilization of global prices after they hit rock bottom, as well as the expected correction of the ruble exchange rate.
Source: CCA