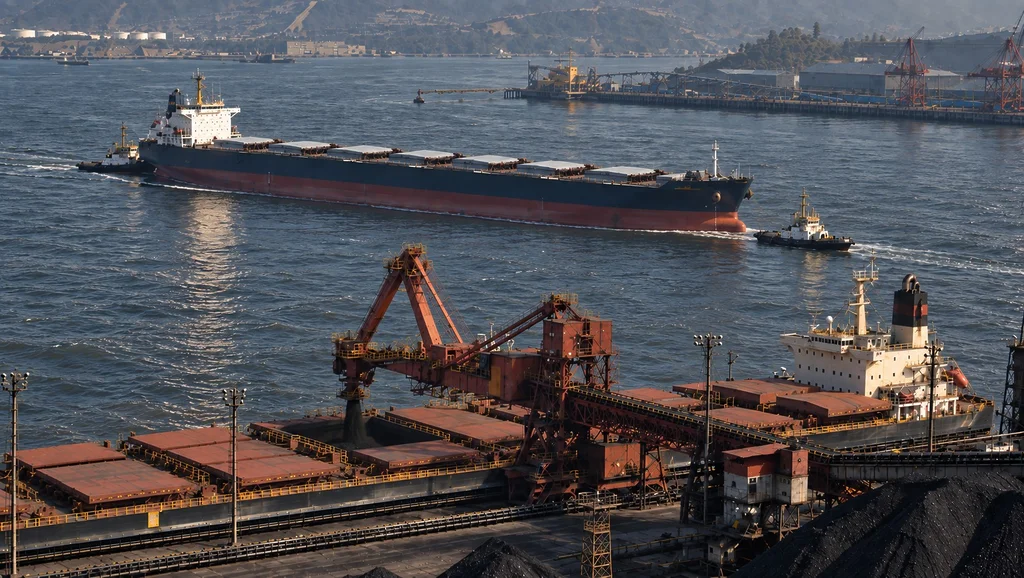
Russian coal exports to China continued to decline in Jan-Aug 2026 as high logistics costs, sanctions and stronger competition from other suppliers weighed on trade.
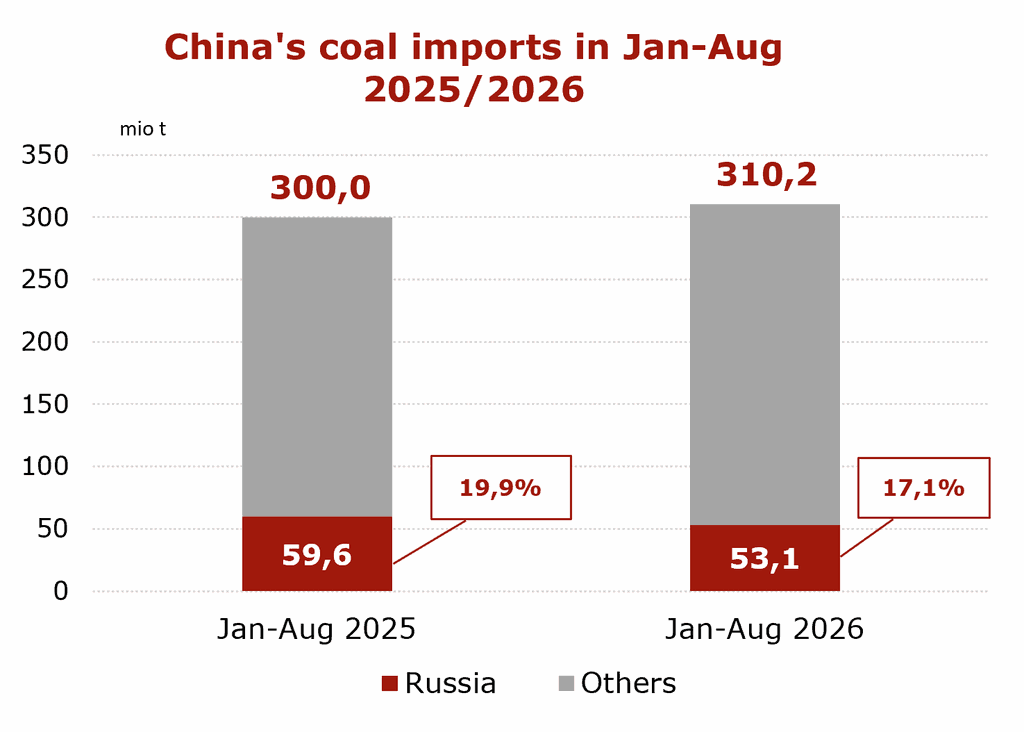
In January-August 2026, Russian coal supplies to China dropped to 53.1 mio t (-6.5 mio t or -10.9% vs. January-August 2025), according to the General Administration of Customs of China (GACC).
The decrease in Russian coal supplies resulted from high railway tariffs, logistical issues, international sanctions and ruble appreciation. Given depressed global prices, these factors are forcing most producers to export coal at zero or negative margins, which will likely lead to further production and supply cuts in the near term.
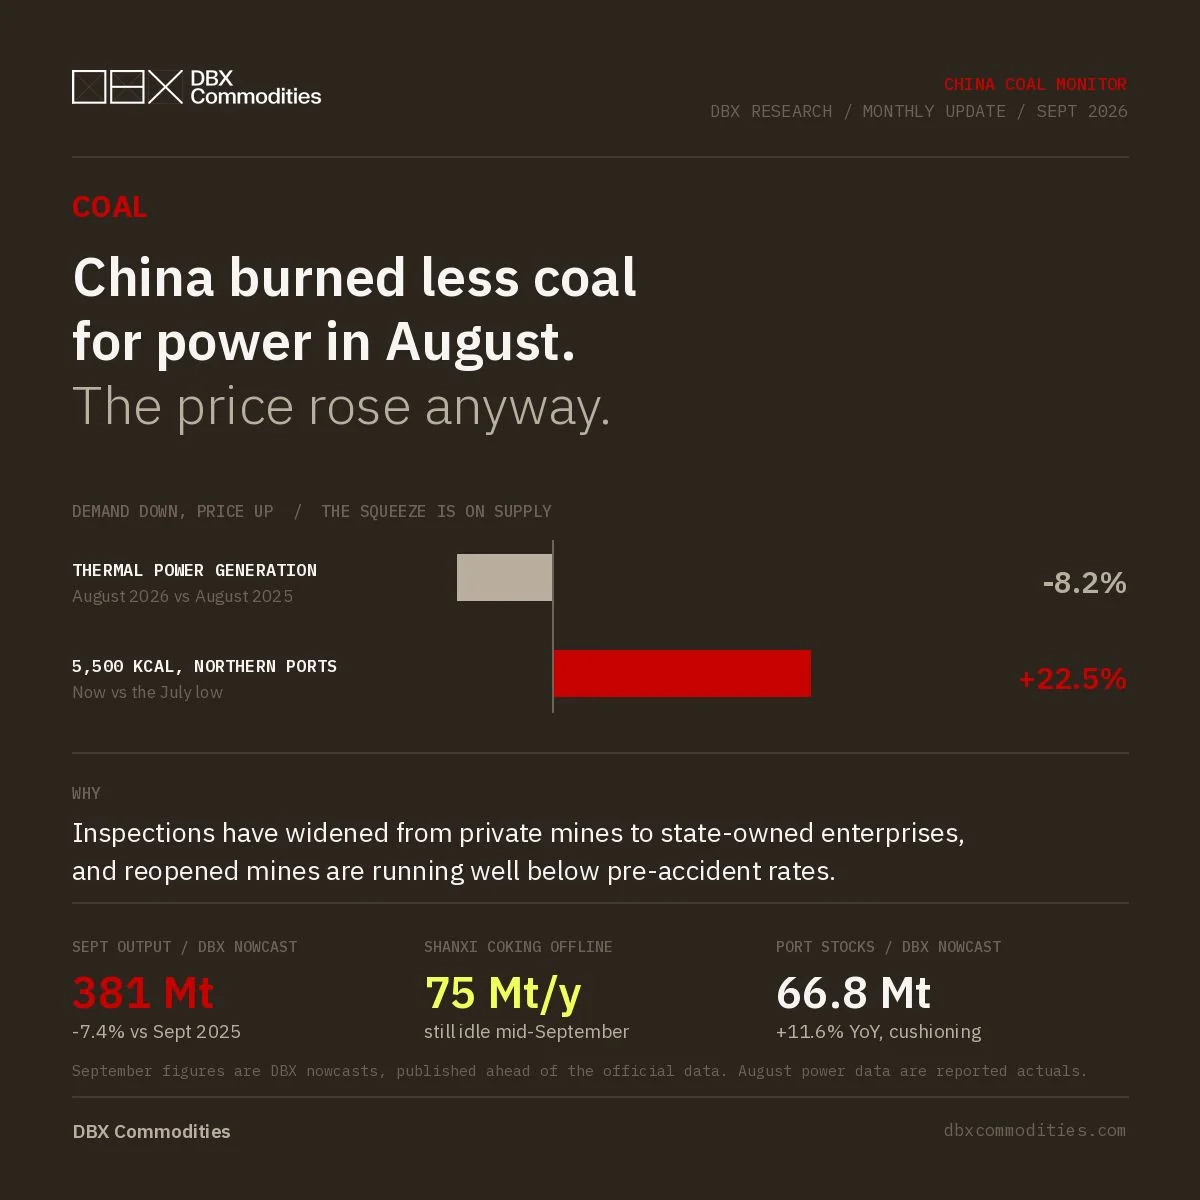
In January-August 2026, China’s total coal imports amounted to 310.2 mio t (+10.2 mio t or +3.4% vs. January-August 2025).
In August 2026, Chinese coal mining companies produced 361.8 mio t (+5.4% m-o-m or -8% y-o-y). In January–August 2026, total coal output fell to 3.06 billion t (-3.3% y-o-y).
Indonesia, China’s largest coal supplier, in January-August 2026, reduced its exports to 120.7 mio t (-1.1 mio t or -0.9% y-o-y).
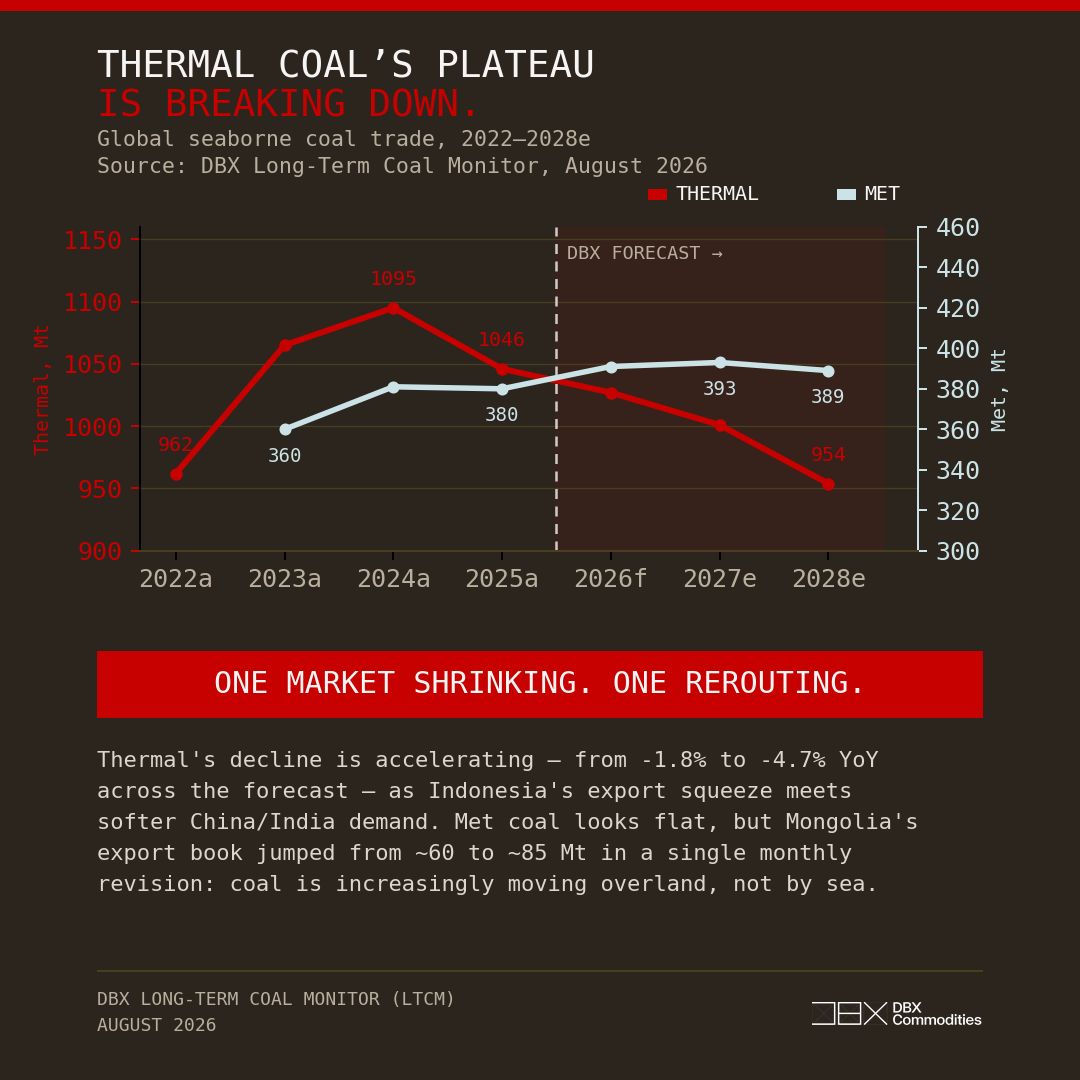
In January-August 2026, Mongolia continued to boost its coal shipments to 78.4 mio t (+25.8 mio t or +49.0% y-o-y), securing its second place among coal exporters to China.
It is followed by Russia, which was the second-largest supplier after Indonesia last year.
Australia slipped to the fourth place, exporting 48.1 mio t (-0.8 mio t or -1.6% y-o-y).
Market share shifts among major suppliers (Jan-Aug 2025/2026):
Despite strong demand, Russian coal exports to China continue to decline due to systemic issues and crisis in the coal industry, potentially leading to Russia’s shrinking market share and growing competitive pressure from other suppliers.
Source: CCA